Green Dot - Mobile Banking

Screenshots
Details
- Rating
- 32.77K reviews
- Version
- 4.69.5
- Developer
- Green Dot
Analysis by Norviv
I approached Green Dot - Mobile Banking as a practical finance app rather than a feature checklist. Developed by Green Dot, it is aimed at people who want to handle everyday banking from a phone, with the convenience of checking their money without making a trip somewhere. My overall impression is useful but qualified: the app can make routine money management easier, yet the experience depends heavily on whether its interface, account options, and support flow match your personal situation.
It is free to download and carries an Everyone age rating, which makes the basic proposition approachable for a wide audience. The app has been available since May 17, 2011, and its current version is 4.69.5 for devices running Android 7.0 or later. That long presence matters because this is not a brand-new experiment, but it also means expectations are higher: a finance app needs to feel dependable, clear, and calm whenever a user is worried about a payment or their available balance.
How Green Dot works in everyday banking situations
The strongest reason to consider Green Dot is convenience. I can see the appeal for someone who wants a phone-centered way to keep an eye on day-to-day finances instead of relying on paper records or visiting a physical location. A quick check before shopping, reviewing activity after a purchase, or confirming whether money is available can be much less stressful when the information is easy to reach.
That convenience is especially relevant for people whose schedules, transport, work hours, or location make traditional banking inconvenient. A mobile banking app can also help users build a habit of checking their finances more regularly. In my experience, frequent small checks are often more useful than an occasional deep review, because unusual activity or an unexpectedly low balance is easier to notice before it becomes a larger problem.
Green Dot’s store summary, “Your banking. Your choice.”, points toward that flexible, mobile-first idea. I would interpret it as an invitation to manage ordinary banking tasks on your own terms, not as a promise that the app will replace every banking service or every form of personal support. That distinction is important for anyone comparing it with a full-service bank app.
Readability and navigation matter more than visual polish
For a finance app, readable information is more important than decorative design. When I open an app to check money, I want the balance, recent activity, and next action to be understandable without hunting through several screens. Green Dot is most useful when I treat it as a focused tool for routine checks rather than expecting it to explain every financial decision for me.
A sensible personal workflow is to open the app at a quiet moment, review the current balance first, then inspect recent transactions before making a larger purchase. I would not rely on memory alone after that. If something looks unfamiliar, I would pause and investigate through the available in-app route or Green Dot’s official support channels rather than repeatedly refreshing the same screen.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This approach also helps users who find dense financial interfaces tiring. Instead of trying to learn every area at once, begin with the screens you actually need: account status, activity, and help. Once those are familiar, explore other options gradually. That is a small but meaningful accessibility advantage because it reduces cognitive load, particularly for someone who is new to mobile banking or uncomfortable with financial terminology.
The app’s audience is broad, but broad appeal does not guarantee that every label will be equally easy for every person to understand. People with dyslexia, limited reading stamina, attention difficulties, or low confidence with banking may benefit from slowing down and checking each transaction carefully. I would also avoid completing a money-related task while distracted, since a rushed tap can have more serious consequences here than in an ordinary shopping app.
Motor and sensory considerations during real use
Using a banking app involves more than reading. It also requires tapping accurately, entering information, recognizing confirmation states, and noticing when a screen has changed. For users with tremors, limited dexterity, or one-handed phone use, these steps can be frustrating if controls are close together or if the app does not make the result of an action obvious enough.
My practical advice is to use Green Dot while the phone is stable and the screen is free from glare. That sounds simple, but it can make a real difference when entering sensitive details or reviewing a transaction. A larger device may be more comfortable than a small phone for someone with low vision, while a user who depends on spoken screen output should test the most important account and support screens personally before making the app their only banking route.
I would also keep the phone’s own accessibility settings in mind. Text enlargement, display contrast, screen readers, touch accommodations, and voice interaction are controlled largely by the operating system, and their usefulness can vary from one screen to another. I cannot treat those tools as a guarantee that every part of the app will be equally accessible, but they are worth trying before deciding that mobile banking is impossible.
Sensory context matters too. A bright, noisy place is a poor environment for checking financial information, especially if you need to concentrate on transaction details. In a quiet setting, I can review activity with fewer distractions and reduce the chance of confusing one purchase with another. For someone with anxiety around money, that calmer routine may be just as valuable as any individual feature.
Situational access: when the phone is helpful and when it is not
The clearest everyday scenario is a quick pre-purchase check. Imagine standing in a grocery line and trying to remember whether a recent bill has already reduced your available funds. Opening Green Dot can be more practical than searching through messages or reconstructing the week from memory. If the information is clear, the user can make a more informed decision without leaving the store.
Another useful situation is reviewing activity after several small purchases. Small expenses are easy to overlook, and a mobile view can bring them together in one place. I would use that review as a weekly habit, not as a substitute for a proper budget. The app may help me see what happened, while a separate note or budgeting method helps me decide what to change next.
Mobile access is also valuable for people who cannot easily reach a branch, but it introduces a different dependency: the phone, battery, network connection, and login process all become part of the banking experience. If a phone is lost, shared, damaged, or temporarily unavailable, the user may feel locked out of an important routine. I recommend keeping an alternative way to reach official support and knowing where essential account information can be found outside the app.
This is where Green Dot may be less suitable than a traditional bank relationship for some users. If you regularly need face-to-face explanations, help with complicated financial matters, or a broader set of services under one roof, a physical branch or a more comprehensive banking provider may serve you better. The app’s convenience is strongest for independent, routine use; it is not automatically the best answer for every financial need.
What the audience response tells me, and what it does not
Green Dot has an average rating of 3.5 from around 91 thousand ratings, with more than 33 thousand written reviews. That is a substantial amount of public feedback, and I read it as a sign that the app is widely used rather than universally loved. The difference between broad adoption and perfect satisfaction is worth remembering: a finance app can be useful for many people while still producing frustrating experiences for others.
It has passed 5 million installs, which reinforces its reach in the finance category. I would not use that figure as proof that it is the right choice for me, though. Popularity can indicate that the product solves a real problem, but personal fit depends on clarity, reliability in my own circumstances, and whether the account arrangement meets my needs.
The most important comparison is with the usual alternatives. A full bank app may offer a wider range of account products, stronger integration with loans or investments, and access to branch-based assistance. A budgeting app may be better for categorizing spending across several accounts. A spreadsheet may offer more control for someone who wants to design a personal financial system. Green Dot’s advantage is the directness of a mobile banking experience, not necessarily the depth of every alternative.
Remaining barriers before making it your main banking tool
The first barrier is confidence. Financial actions feel high stakes, so an interface that is merely functional may not feel reassuring enough for everyone. New users should take time to learn how balances and activity are presented before depending on the app during an urgent situation. I would begin with observation and simple checks, then move to more involved tasks only after the basic navigation feels familiar.
The second barrier is support. When an account question cannot be solved by looking at recent activity, the quality and accessibility of the next step become crucial. Users who have difficulty with phone calls, small text, fast conversations, or complicated instructions should think about how they prefer to get assistance before they need it. That is not a criticism unique to Green Dot; it is a central issue with any digital financial service.
The third barrier is device compatibility. The minimum operating system is Android 7.0 or later, so anyone using an older Android device should check compatibility before planning around the app. Even on a compatible phone, older hardware, limited storage, or reduced battery life can make a banking workflow less comfortable. Keeping the operating system and app current is sensible, but updates can also change where controls appear, so I would recheck the key screens afterward.
Privacy is another practical consideration. I would avoid opening a financial app on a public or borrowed phone, and I would use the phone’s security options rather than leaving the device openly accessible. Shared devices create an additional risk because another person may see notifications, account details, or recent activity. These habits do not make the app inaccessible; they make mobile banking safer and more predictable in real life.
Users who need highly customized visual presentation, extensive guided explanations, or dependable human assistance at every stage should test Green Dot carefully before switching completely. Likewise, someone seeking advanced budgeting analysis may be happier pairing a banking app with a dedicated budgeting tool. The best choice depends on whether convenience or comprehensive guidance is your bigger priority.
An inclusive verdict for everyday users
I see Green Dot as a reasonable option for people who want straightforward mobile access to everyday banking and are comfortable taking responsibility for checking information carefully. Its free price, Everyone rating, long availability, and broad install base make it easy to consider, while the 3.5 average suggests that expectations should remain realistic rather than blindly optimistic.
For me, the app’s inclusive potential comes from putting routine account checks within reach of people who may not be able to visit a branch easily. Its limitations come from the same source: a phone-based service can become difficult when the device, interface, connection, login process, or support route does not suit the user. Accessibility is therefore not just about whether the app opens; it is about whether a person can complete an important task calmly and confidently.
I would recommend trying Green Dot - Mobile Banking if your needs are centered on convenient account access and you are willing to establish a careful checking routine. Start by testing readability, touch accuracy, device settings, and the support path. If those basics work well, the app can become a useful part of daily money management.
I would skip it as a sole banking solution if you need extensive in-person help, advanced financial planning, or a highly tailored accessibility experience that must be guaranteed in every workflow. In that case, compare it with a full-service bank, a budgeting companion, or a provider with support that better matches your communication needs. My final view is balanced: Green Dot can make banking more reachable, but its real value is determined by how comfortably and safely it fits the person holding the phone.
Frequently Asked Questions
01What is Green Dot Mobile Banking, and who can use it?
Green Dot Mobile Banking is a financial app designed for managing eligible Green Dot accounts from an Android or iOS device. After signing in, users can typically view balances, review transactions, deposit checks where supported, transfer money, and manage certain card settings. Availability depends on the specific Green Dot product, account status, identity verification, location, and the features offered with that account.
02Is Green Dot Mobile Banking free to download and use?
The app is generally free to download, but downloading it does not mean every banking service is free. Depending on your Green Dot account and the transaction you choose, fees may apply for services such as cash reloads, out-of-network ATM withdrawals, expedited transfers, or other optional features. Before completing a transaction, carefully review the displayed fee, account terms, and current pricing information.
03Can I deposit checks or add cash through the Green Dot app?
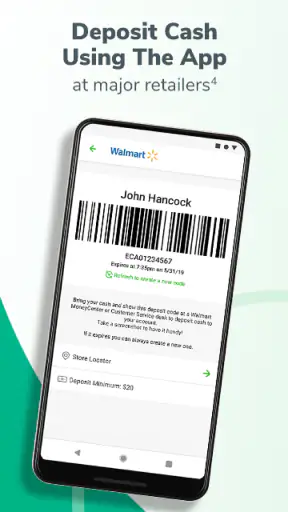
Green Dot may provide mobile check deposit and cash-loading options, but availability is not identical for every user or account. Mobile check deposits can require photographing the check, meeting eligibility conditions, and waiting for funds to become available. Cash deposits may be made at participating retailers, sometimes with a fee. Always confirm supported locations, limits, and processing times inside the app.
04How secure is Green Dot Mobile Banking?
The app uses standard account-security measures such as password or passcode protection, identity verification, encrypted connections, and alerts for account activity. However, no mobile banking service is completely risk-free. Use the official app store version, keep your phone and operating system updated, avoid sharing verification codes, and contact Green Dot promptly if you notice an unfamiliar login, transfer, card transaction, or other suspicious activity.
05What should I do if I cannot log in or my card is lost?
If you cannot access your account, use the app’s password or username recovery options and make sure your contact information is current. Repeated failed attempts may temporarily restrict access, so avoid guessing credentials repeatedly. For a lost, stolen, or compromised card, use the app to lock or manage the card when available and contact Green Dot through its official support channels as soon as possible.


